Biometric Credit Scoring See the Risk Your Data Can't
This site is protected by reCAPTCHA and the Google Privacy Policy and Terms of Service apply.

Every borrower has an invisible signature
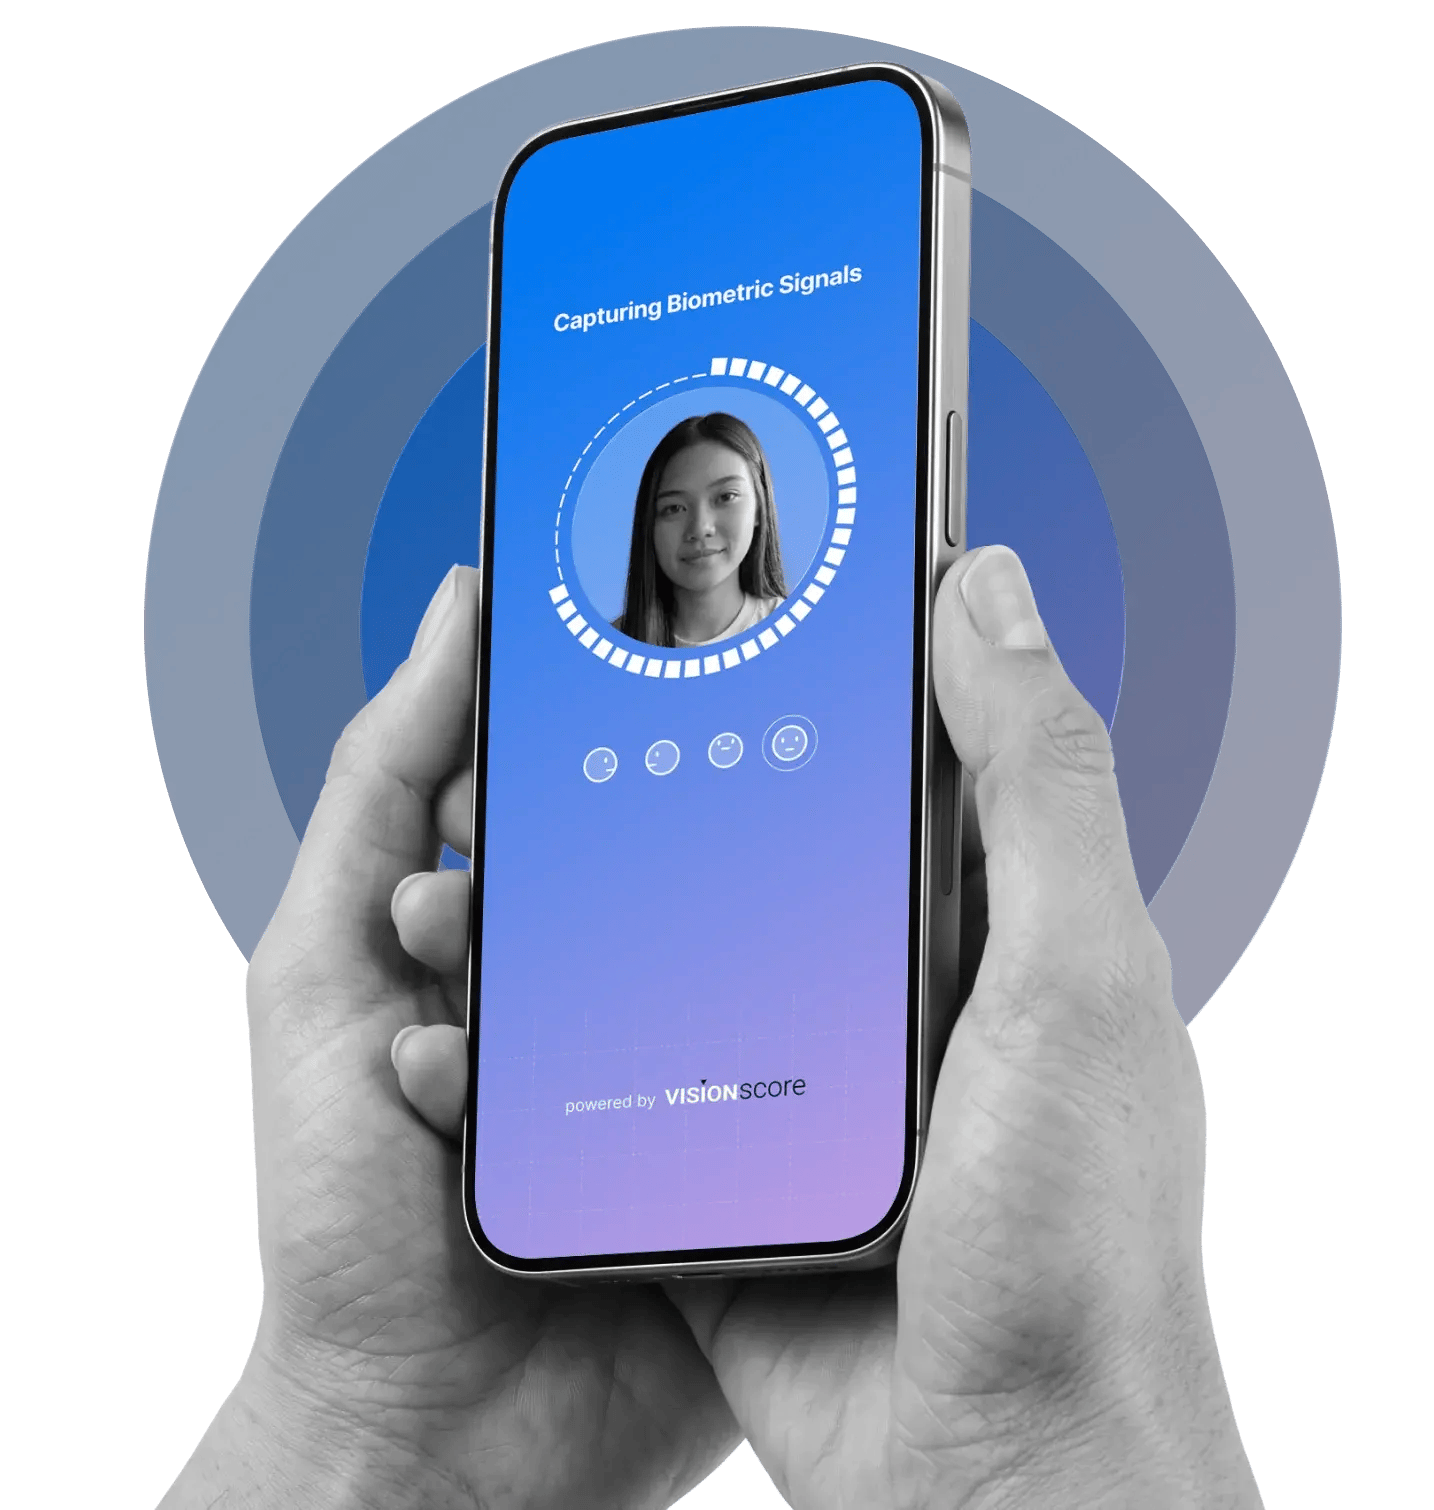
At the point of application, Vision Score captures real-time biometric signals—unique and invisible to traditional models
Identify risk that historical data misses
Vision Score flags hidden default risks in profiles that appear safe by every historical measure, reading the "present moment" signals that standard models were never built to see.
Score the borrowers no one else can
For thin-file applicants, Vision Score analyzes onboarding cues—liveness, age, and environment—to generate a standalone risk score with no extra steps or infrastructure.
A more accurate, wider portfolio
By pairing historical data with real-time biometric signals, you surface hidden risk and score the "invisible" borrower. Fewer defaults, more approvals.
The AI Advantage
A new category of credit risk intelligence
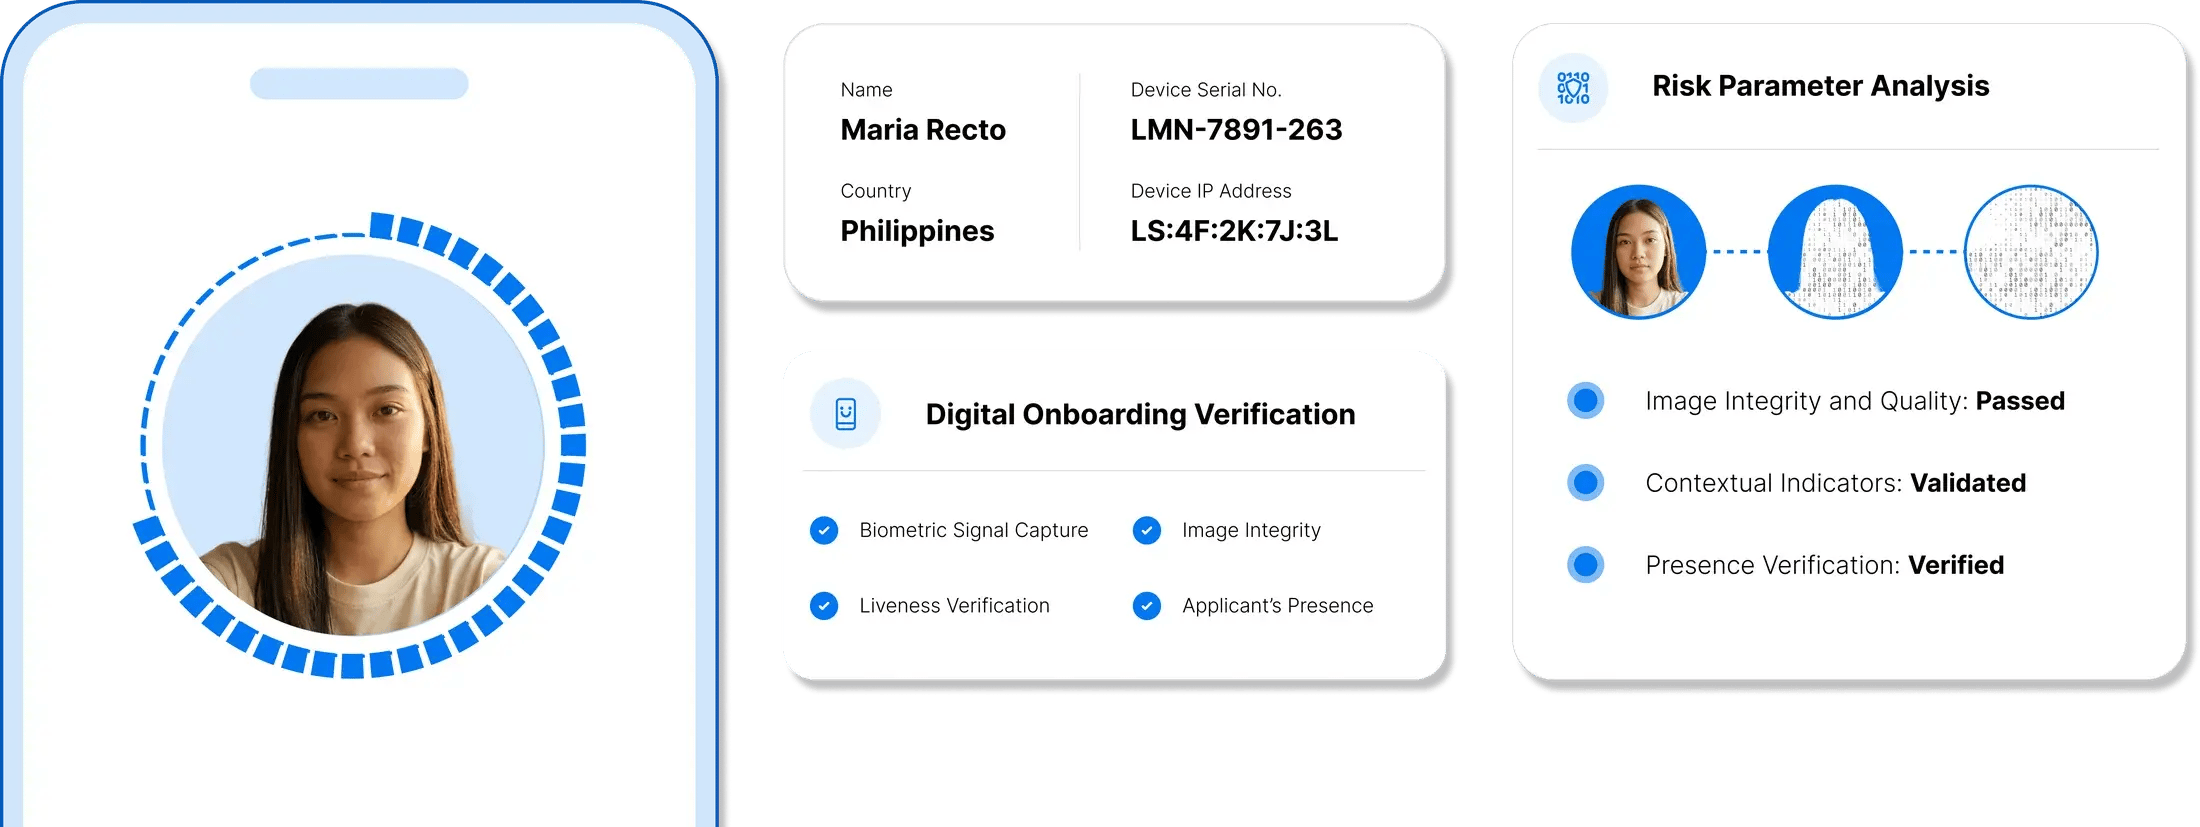
How Vision Score Works
Five stages. One score.
Every borrower produces a biometric signal at the moment they apply.
Biometric Signal Capture
Captured within your workflow
Liveness Verification
Deepfake, mask & spoofing detection
Risk Parameter Extraction
Validated against real loan performance data
Score Calculation
Trained and calibrated on your institution's data
Decision Integration
Integrated score into your lending workflow


The borrowers your bureau file can’t see
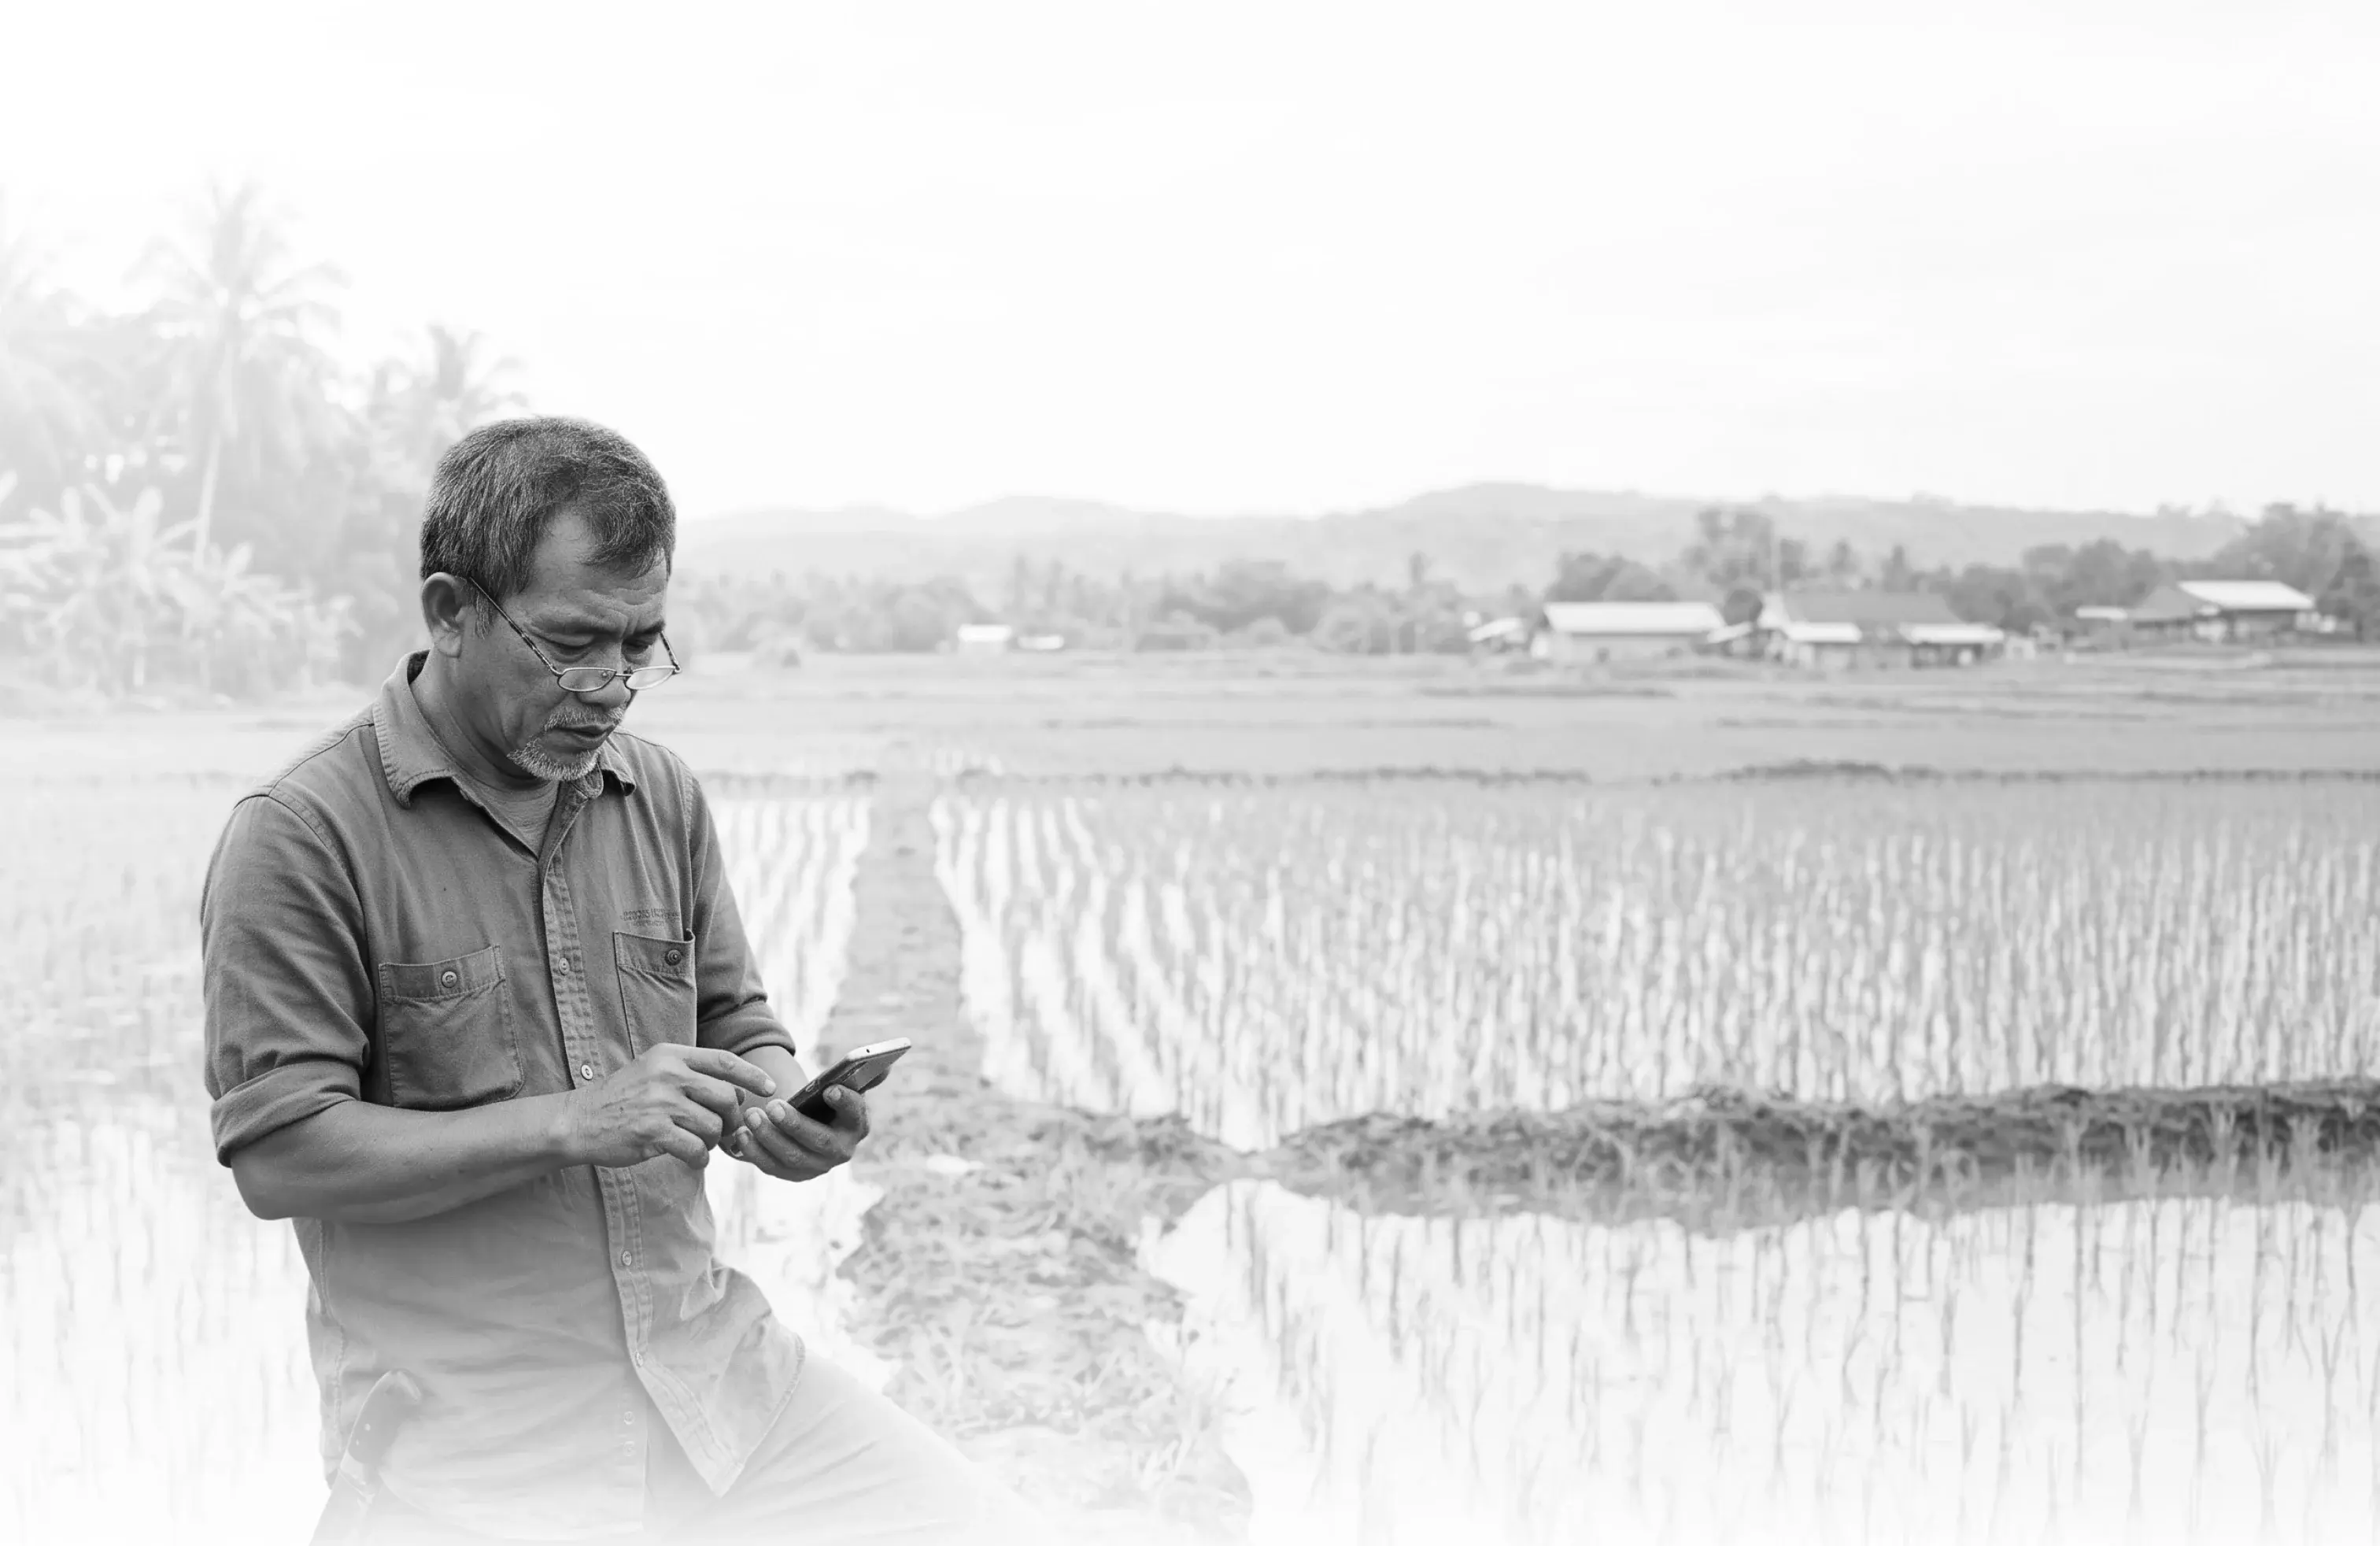
Most Filipino adults have never held a credit card or a formal loan, so the bureau returns nothing on them. Not a poor score — no file at all. A rice farmer with twenty years of harvests behind him and a salaried applicant two months into her first job look identical in that lookup, and most models treat them the same way: decline.
Vision Score reads a signal that exists whether or not a bureau file does. It assesses the applicant at the moment they apply, from the capture your onboarding flow already takes, so a thin file stops being the end of the assessment. The question moves from whether you have history on this person to whether you can tell what kind of borrower they are — which is the question you were trying to answer in the first place.