The harder you make it for a fraudster to get in, the more likely you are to lock out the very customers who keep your lights on.
The industry has a dirty little secret: we’ve been taught that security is a wall. We build it higher, add more shards of glass at the top, and wonder why our conversion rates are cratering. But a wall doesn't distinguish between a burglar and a homeowner who forgot their keys. It just stands there, indifferent and stubborn. For years, the trade-off was accepted as a natural law of physics—if you want to be safe, you have to be slow. That era is over. In 2026, when everyone expects things done fast and without fuss, friction is a silent brand killer.
The Cost of a Clean Ledger
Think about a mother in Iloilo trying to send emergency tuition funds to her son in Manila. She’s used your app regularly for three years. Suddenly, a rigid, legacy "step-up" check triggers because she’s on a new device. She’s asked to re-upload her ID. The SMS OTP arrives ten minutes late. By the time she’s "verified," she’s already closed the app and used a competitor. Her son misses his payment deadline.
A risk officer wouldn't know it. The system worked; no fraud occurred. But to the CEO, this is a disaster. You didn't just lose a transaction; you drained your trust equity. In the Philippines, where digital payments made up 57.4% of retail payment volume in 2024, one "glitchy" experience can devalue millions in marketing spend. We are seeing a massive soft drain—users migrating not to the cheapest service, but to the one that respects their time.
The Regulatory Squeeze
As we move through 2026, the Bangko Sentral ng Pilipinas (BSP) has shifted the burden with the Anti-Financial Account Scamming Act (AFASA). The liability shift is real. Institutions are now legally tethered to the protection of the consumer journey, transforming cybersecurity from a back-office expense into a front-line fiduciary duty. (We break down what that means in practice in AFASA Compliance Is the Floor.)
A typical reaction is adding more friction. More checks. More document uploads. But while you’re busy complying with the letter of the law, your "fraud-to-friction" ratio is spinning out of control. PwC’s 2025 Global Digital Trust Insights reveal that despite high cyber budgets, organizations still struggle with implementation—only 2% of financial institutions have achieved enterprise-wide resilience. When security feels like an interrogation, customers walk. Deloitte's 2025 Outlook highlights that the winner isn't the one with the most security, but the one with the most resilient retention. When we’re winning the battle against bots but losing the war for the Filipino consumer, we’re not doing our jobs right.
Security as a Social Contract
Trust is a dynamic negotiation. When a customer joins, they enter a social contract: I give you my data, you give me a seamless life. High-friction environments break this contract and lead to Internal Fatigue. When risk systems flag too many "false positives," manual review teams become overwhelmed. They miss actual sophisticated deepfakes because they were too busy manually verifying a legitimate grandmother whose ID was slightly blurry. Friction doesn't just annoy customers; it blinds your defenders.
Reclaiming the Journey
- Deploy Intent-Based Friction: Stop treating every user like a suspect. Use risk scoring to decide who needs an extra check and who doesn't, so friction lands only where the risk is.
- Audit the Drop-off Points: If your onboarding abandonment is climbing, your tech is likely the culprit, not your compliance requirements. A "safe" journey that no one completes is a failed business strategy.
- Unify the Data Pulse: The biggest mistake is treating KYC and Transaction Monitoring as separate silos. One is the "door," the other is the "hallway." They should share the same brain.
Frictionless Transaction Verification With TrustVision
This is where the math changes. At Trusting Social, we don't believe in walls; we believe in invisible, intelligent boundaries. With TrustVision, KYC and transaction monitoring work from the same identity.
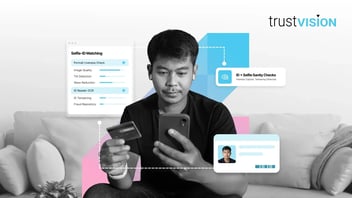
The face verified at onboarding becomes the customer’s anchor. Each new event is scored against a database of known fraud attempts and device and behaviour signals, so routine, low-risk payments go straight through. Only the moments that carry real risk—a large transfer, a new payee, a new device—trigger TrustVision transaction verification: a quick live face check instead of an SMS OTP that can be intercepted or phished.
We don't ask the mother in Iloilo to prove who she is five times. Her everyday transfers run without interruption, and when something does look unusual, one glance at her phone settles it. Security becomes a silent guardian—fast and quiet.
In the boardroom, we talk about "risk mitigation." On the street, people talk about "hassle." If your brand becomes synonymous with hassle, no amount of security will save your market share. True leadership in 2026 is recognizing that the most secure transaction is the one the customer barely noticed being verified.
Is your onboarding a welcoming door or a locked gate? It's time to decide which one defines your brand.
Where to Start
Want to see how much friction you could take out of your transaction flows without opening the door to fraud? Talk to our team and bring your hardest case.